September 18, 2026
Bankruptcy & Insolvency in the UAE: When Restructuring Can Still Protect the Business
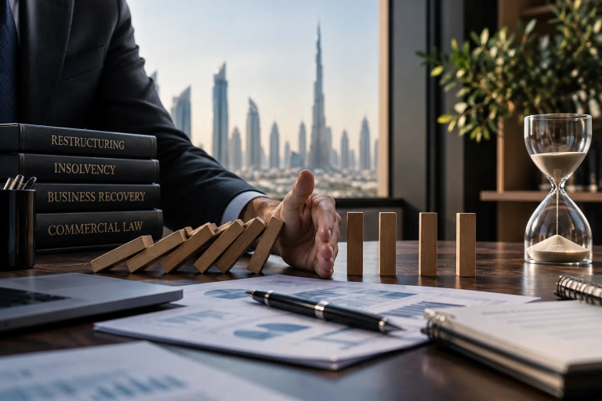
Early restructuring advice can preserve options before financial distress becomes liquidation.
Financial difficulty rarely begins with a single event. A business may first experience delayed receivables, overdue supplier payments, missed loan instalments or difficulty meeting payroll and operating expenses. If those pressures continue, management may need to consider whether the problem is temporary or whether the company's financial position requires a formal restructuring process.
The UAE bankruptcy framework provides different procedures depending on the circumstances of the debtor and whether the business remains viable. Federal Decree-Law No. 51 of 2023, together with Cabinet Resolution No. 94 of 2024, regulates preventive settlement, restructuring and bankruptcy procedures.
The federal framework does not apply identically in every situation. Certain entities and businesses operating under separate insolvency regimes may fall outside its scope, including entities in financial free zones where their own insolvency laws apply. The applicable jurisdiction should therefore be established before any procedure is considered.
Financial Distress Does Not Automatically Mean Liquidation
A company experiencing serious financial pressure does not necessarily have to move directly towards liquidation. The law provides procedures intended to address financial difficulty while preserving a viable business where possible.
Preventive settlement and restructuring are different from bankruptcy. They focus on dealing with debts while allowing a business capable of continuing to operate to seek an arrangement with creditors. Bankruptcy applies where the statutory conditions are satisfied and the business is no longer viable.
This distinction is important when obtaining advice from a bankruptcy lawyer. Cash flow, outstanding liabilities, secured debt, creditor action, existing contracts and the company's future operating position should all be examined before deciding which process may be appropriate.
Preventive Settlement Can Leave Management in Control
Preventive settlement may be available where the debtor's business remains viable and the financial conditions required by the law are present. These may include cessation of payment or circumstances indicating that the debtor expects to become unable to meet debts when they fall due.
The application is made by the debtor. One of the significant features of preventive settlement is that management generally remains responsible for the business and its assets in the ordinary course unless the Bankruptcy Court decides otherwise.
Transactions outside the ordinary course of business require court approval. This can make preventive settlement relevant for a company that still has a workable business model but requires time and creditor cooperation to deal with its financial position.
A Stay on Claims Can Provide Time to Develop a Proposal
Once preventive settlement proceedings are opened, claims are generally suspended for three months from the date of the court's decision. The Bankruptcy Court can extend the suspension in periods of up to one month, subject to a maximum overall period of six months.
The stay gives the debtor time to work towards a settlement rather than simply postponing creditor action. Financial information must be organised, creditors must be provided with the information required by the process and the proposed settlement must be capable of securing the necessary support.
A company entering the process without reliable accounts, realistic forecasts or a workable proposal may find that the additional time does little to solve the underlying financial problem.
Restructuring Brings Greater Trustee Supervision
Restructuring is a separate procedure that can be requested by the debtor, qualifying creditors or the relevant regulatory authority where the conditions under the law are satisfied and the business remains viable.
The debtor generally continues operating the business, but under the supervision of a restructuring trustee unless the Bankruptcy Court orders otherwise. The trustee can review financial operations and obtain information about the debtor's assets, liabilities and business activities.
This creates a greater level of external oversight than preventive settlement. The objective, however, remains focused on determining whether the business can continue under a restructuring plan rather than moving immediately to liquidation.
Creditors Have Their Own Decisions to Make
Insolvency proceedings affect lenders, suppliers, landlords and other creditors as much as they affect the debtor. A creditor may need to decide whether ordinary debt recovery remains effective or whether participation in a formal restructuring or bankruptcy process is more appropriate.
Cabinet Resolution No. 94 of 2024 establishes financial thresholds for creditor applications. For an ordinary creditor, or a group of ordinary creditors, the unpaid debt required to apply for restructuring or bankruptcy is generally at least AED 1 million. Other requirements also apply, including conditions concerning the nature and status of the debt, and different thresholds can apply in other categories of cases.
For businesses comparing law firms in UAE insolvency matters, creditor-side advice may include proving a debt, reviewing a proposed restructuring plan, considering security rights and determining whether the requirements for initiating formal proceedings have been satisfied.
Directors Should Act Before the Financial Position Deteriorates Further
Article 15 of Federal Decree-Law No. 51 of 2023 allows a debtor to apply for preventive settlement, restructuring or bankruptcy within 60 days from cessation of payment or from becoming aware of information indicating that it will be unable to pay its debts when they fall due.
Importantly, failing to submit the application within that period does not, by itself, make a later application inadmissible. The provision should therefore not be described as an automatic 60-day bar after which restructuring becomes unavailable.
Management should nevertheless take repeated payment problems seriously. Early financial and legal assessment can provide a clearer view of the company's liabilities, creditor exposure and whether the business has a realistic prospect of continuing. This is often the starting point for top legal firms in Dubai advising on financial distress.
Bankruptcy Applies Where the Business Is No Longer Viable
The distinction between restructuring and bankruptcy ultimately depends on more than the existence of unpaid debts. Under the federal framework, bankruptcy proceedings are initiated where the applicable statutory conditions are met, including inability to repay debts, a deficit in the debtor's financial position and the business being non-viable.
Conclusion
Where the business can still operate sustainably, preventive settlement or restructuring may offer an alternative. Where viability has been lost, the legal focus can shift towards liquidation of the debtor's assets and distribution to creditors through the bankruptcy process.
Businesses assessing top law firms in Dubai should therefore look for insolvency advice that considers both the statutory procedure and the commercial position of the company.
AY Advocates advises companies, directors, shareholders and creditors on financial distress, debt recovery, preventive settlement, restructuring and bankruptcy matters in the UAE. Financial pressure can reduce the options available as creditor action increases.
Frequently Asked Questions
1. Does financial difficulty automatically mean a UAE company must enter bankruptcy?
No. Preventive settlement and restructuring may be available where the business remains viable and the relevant statutory requirements are satisfied.
2. Can a company continue operating during preventive settlement?
Yes. The debtor generally continues managing its business and assets in the ordinary course unless the Bankruptcy Court decides otherwise. Transactions outside the ordinary course require court approval.
3. Are creditor claims suspended during preventive settlement?
Yes, generally. Opening preventive settlement proceedings creates an initial three-month stay on claims. The court may extend the stay, but the overall period cannot exceed six months.
4. Who can request restructuring in the UAE?
The debtor, qualifying creditors or the relevant regulatory authority may request restructuring where the statutory conditions are satisfied and the business remains viable.
5. Can a creditor apply for a company's bankruptcy?
Yes. A qualifying creditor may apply for restructuring or bankruptcy where the requirements under the law and Executive Regulations are met. For an ordinary creditor or group of ordinary creditors, the applicable unpaid debt threshold is generally AED 1 million.
6. When should a business seek insolvency advice?
A business should consider legal advice when payment delays become recurring, creditor pressure increases, cash flow is insufficient to meet upcoming liabilities or management has concerns about the company's ability to continue operating. An early review can establish whether restructuring, preventive settlement or another course remains available.